Labor share is at rock bottom, but the outlook is brightening

Summary
- US corporate profits’ share of GDP is at its highest since World War II, while labor’s share of national income is historically low. Strong earnings growth has been led by energy and technology.
- TS Lombard’s Dario Perkins views the recent weakness in labor’s share mainly as a cyclical unwind of post-COVID hiring, rather than a structural effect of AI. He expects tighter labor markets, faster wage growth and a recovery in labor’s share next year.
- Perkins expects AI to complement workers rather than replace them, with productivity gains likely to arrive more slowly than anticipated. If AI becomes a commodity, its benefits may flow to users and be shared between profits and wages across other industries.
This content is generated by AI. You can give feedback on it in the Inderes forum.
Automatic translation: Originally published in Finnish 12/11/2026, 05:33 GMT. Give feedback here.
US employment figures painted a mixed picture from the employee's perspective: the employment situation improved further in October, while at the same time wage growth slowed down, a trend that has been ongoing for several years. What is driving this? Is it the "market share" eaten away by AI in a labor market where the employee is at a disadvantage, or something else?
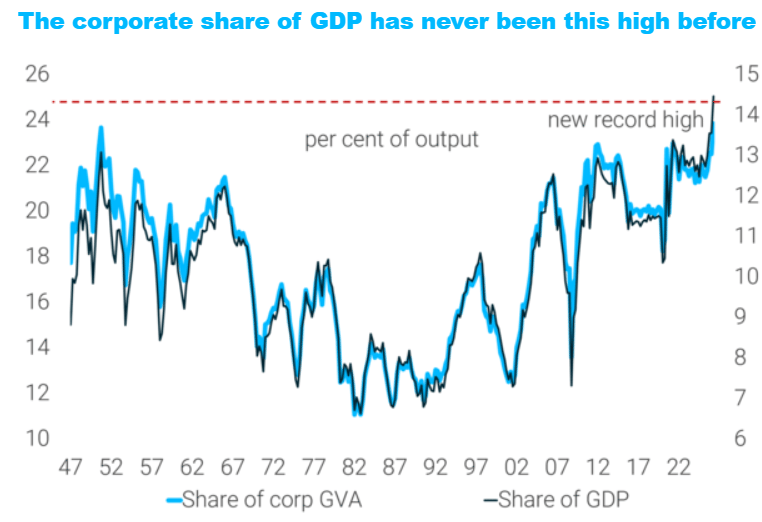
Source: TS Lombard
The US stock market has weathered bad news exceptionally well this year because corporate earnings have grown strongly. According to national accounts, the share of corporate profits in GDP is now the highest since World War II. Growth has been driven by the energy sector and, above all, technology. However, tech earnings tell us more about cash flows than productivity: hyperscalers are investing more than one trillion dollars a year in AI, and one company's investment is another's revenue.
I recently read a very interesting article from TS Lombard, in which Dario Perkins estimates that corporate earnings growth has likely peaked. The support from energy prices is fading, and the growth of AI investments is slowing down. Perkins' central argument, however, concerns who will ultimately end up benefiting from AI, and his answer is comforting to many: wage earners.
Labor share is at rock bottom
When the share of profits in national income is at a record high, the labor share is correspondingly at a historically low level. In 2024–2025, companies increased production through efficiency gains and barely hired new employees, which kept wage pressures moderate. Many analysts interpreted this development as a structural change caused by AI. According to Perkins, however, it was more of a cyclical phenomenon as the post-COVID recruitment boom unwound.
US: Labor share of national income and neutral rate estimates
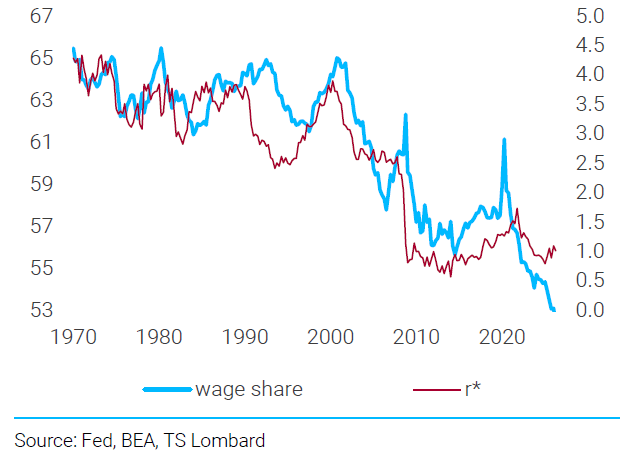
Source: TS Lombard
Next year, however, the situation will change. There is less room left for efficiency gains, so companies will have to hire more employees. Immigration restrictions, in turn, limit labor supply. TS Lombard thus predicts that the labor market will tighten, wages will accelerate, and the labor share will begin to recover. This investment view runs counter to the Wall Street consensus, which expects AI to curb wages – and is very comforting for the consumer.
Greenspan's mistake
AI optimists compare the current situation to the mid-1990s. Alan Greenspan, the Fed Chair at the time, recognized the productivity boom missing from the statistics before anyone else. However, he assumed that "traumatized" employees would not be able to demand wage increases and that the benefits of IT would end up with companies. He was wrong: wages rose in tandem with productivity, and the share of profits in GDP decreased.
TS Lombard's Perkins expects AI to develop in the same way. According to him, AI complements work rather than replaces it. When technology makes an employee more productive, some of the benefit ends up in wages.
Nor will the companies developing AI necessarily capture the benefits for themselves. Chinese open-source models are only a few months behind the frontier, and an abundance of new computing capacity is on the way. Therefore, AI risks becoming a commodity. In that scenario, the benefits will ultimately flow to the users of the technology, and their distribution between profits and wages will be determined in other industries.
The productivity benefits of AI will likely materialize more slowly than expected. Near-term wage growth is therefore driven above all by a tightening labor market. In the longer term, however, AI could reverse the decades-long trend of a declining labor share of national income.
TS Lombard's views are a welcome relief to the current debate, which focuses mainly on job losses caused by AI. It is also true that the post-pandemic labor market imbalance and its unwinding have certainly been underestimated in the United States. It will therefore be interesting to see what the employment and wage figures look like next year, i.e., whether we will see relief in the consumer sector.

