Finnish fund sales subdued in October


Summary
- Domestic fund assets rose by ~1.1 BEUR to 225 BEUR in October, but net subscriptions were only ~45 MEUR, the weakest since March. Market gains of ~1.1 BEUR (+0.5%) drove almost all the increase.
- Net subscriptions in August–October totaled just under 0.5 BEUR. Despite the slowdown, year-to-date inflows were 6.4 BEUR and trailing 12-month inflows nearly 9 BEUR.
- October was weak for most covered asset managers. Aktia’s 117 MEUR outflow mainly reflected redemptions from a passive US fund, while Alexandria and Evli inflows remained below normal levels.
- eQ recorded 54 MEUR of outflows, with trailing 12-month flows near -500 MEUR. UB’s group outflows exceeded 30 MEUR, and the analyst said its figures would be weaker if postponed redemptions were included.
This content is generated by AI. You can give feedback on it in the Inderes forum.
Translation: Original published in Finnish on 11/10/2026 at 4:23 pm EET.
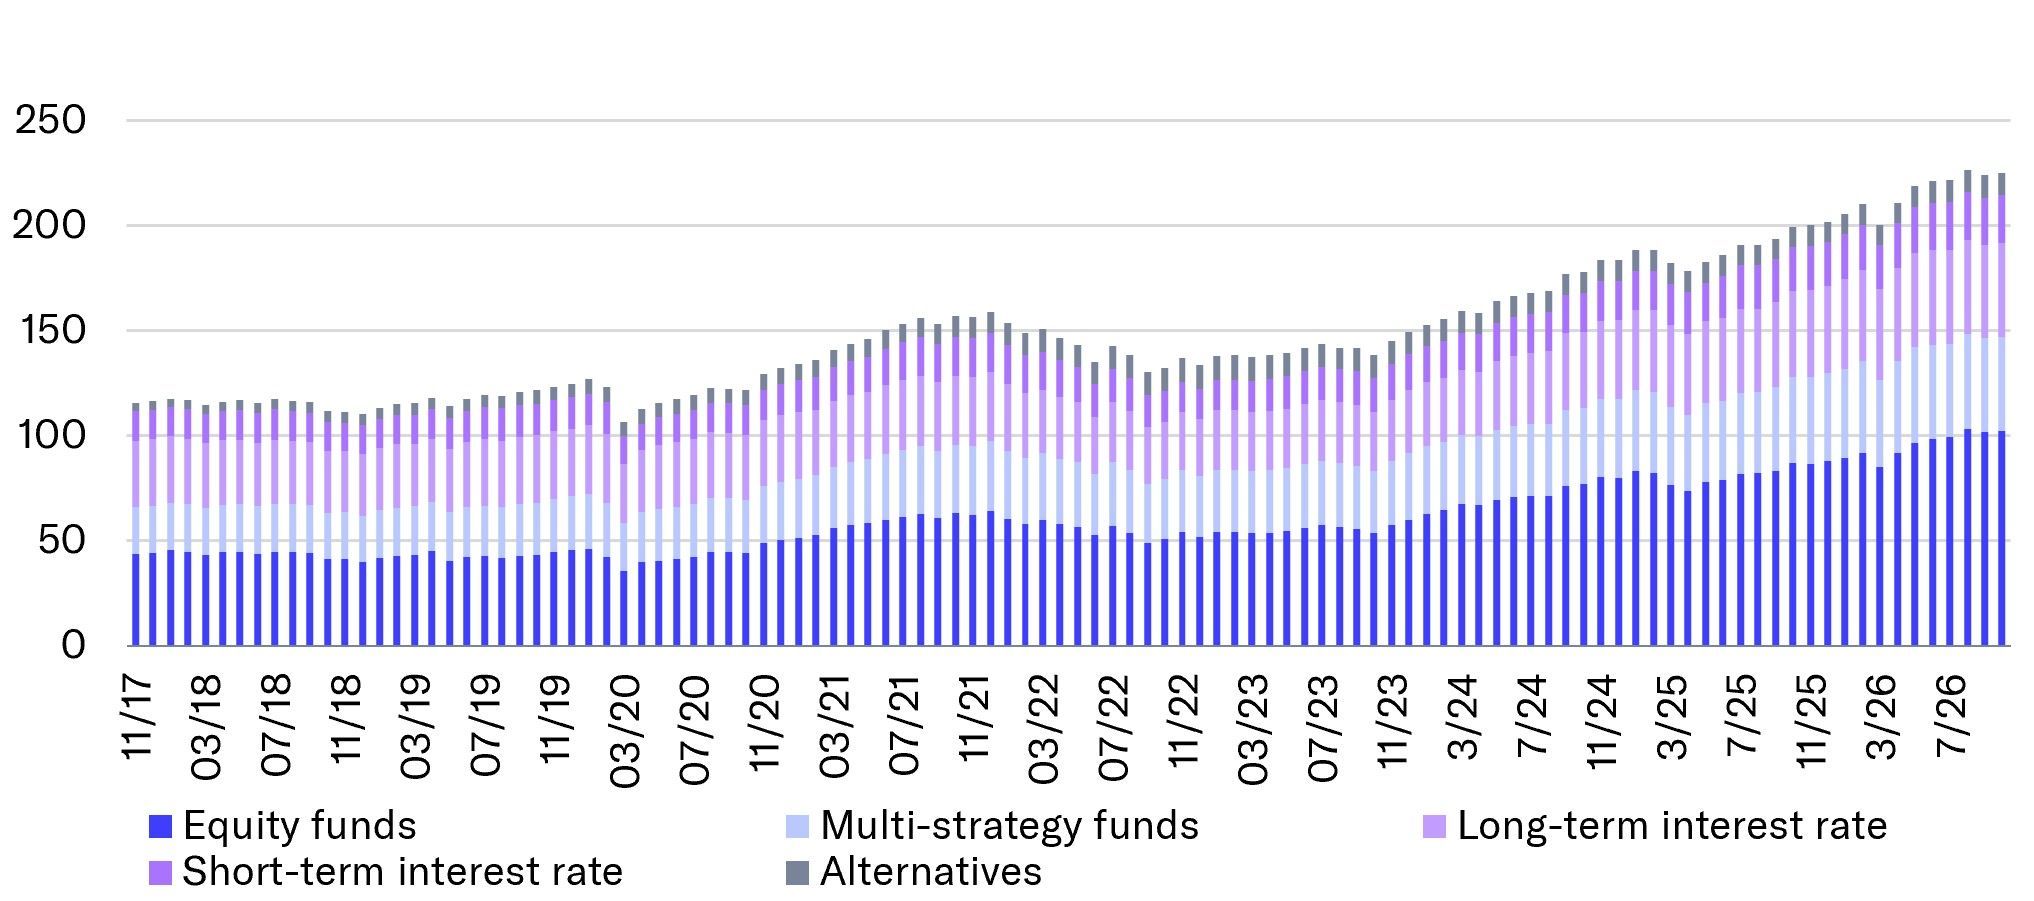
According to the Fund Report published by Investment Research Finland, domestic fund assets rose by ~1.1 BEUR in October to 225 BEUR. Sector-wide net subscriptions were positive by only ~45 MEUR, the weakest figure since March and well below the trailing 12-month monthly average of ~730 MEUR. The increase in assets therefore came almost entirely from market value changes, which were positive by ~1.1 BEUR (+0.5%). Increased market uncertainty has clearly rubbed off on investors this fall. In earlier bouts of market volatility, the impact on fund sales remained small, but the current sharp move in interest rates has made investors clearly more cautious.
Sales in the domestic fund market have slowed significantly since the summer, with net subscriptions for August–October totaling just under 0.5 BEUR. LTM net subscriptions are still positive at nearly 9 BEUR, and year-to-date net subscriptions stand at 6.4 BEUR, which remains an excellent level.
Capital of Finnish investment funds (BEUR)
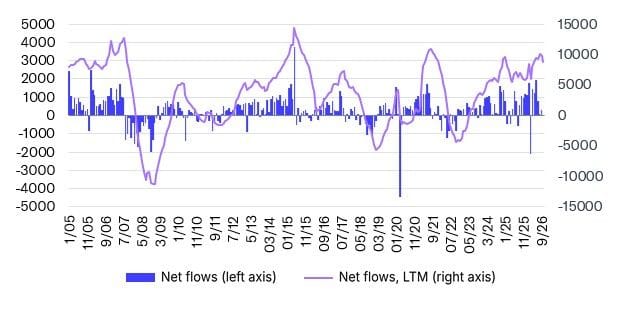
Net subscriptions of Finnish investment funds (AUM)
Weak October for listed asset managers
October was mostly weak for the companies we cover, and customer caution clearly continued amid the fall’s market volatility. Note that in this review, we comment only on covered companies that report up-to-date monthly figures in the Fund Report. Taaleri, Mandatum, and CapMan are therefore excluded. We cover Titanium quarterly in separate reviews, in line with its own reporting cycle.
Aktia's net subscriptions were ~117 MEUR negative in October. This is practically entirely explained by redemptions of ~110 MEUR from the Aktia Passiivi USA fund, and adjusted for this, net subscriptions in other funds were slightly negative. Because the redemptions were directed at a low-fee passive fund, their impact on Aktia's commission income is limited. For the past 12 months, net subscriptions in the funds visible on Aktia's fund report dropped to ~110 MEUR, which is a modest level for Aktia. We remind, however, that the fund report does not tell the whole story for Aktia. New sales in asset management were positive in Q3 for the sixth consecutive quarter (124 MEUR), even though net subscriptions shown in the fund report were slightly negative at the same time.
Alexandria's net inflows were up by 4 MEUR, and sales were once again evenly distributed across different products. However, the level remained slightly below the company's historical normal level. Net subscriptions for the past 12 months remain at only around 20 MEUR, which is a very weak level for the company. The company therefore still faces clear pressure to show concrete results from asset management in the H2 numbers.
eQ's net subscriptions were down by 54 MEUR, meaning redemptions continued for the third consecutive month. The redemptions were once again distributed broadly across various funds, coming from both equity funds (~35 MEUR) and fixed income funds (nearly 20 MEUR). We estimate that these are still larger institutional mandates where eQ has lost in competitive bidding during the year. Net flows for the current year are now at around -460 MEUR and for the past 12 months at roughly -500 MEUR, which corresponds to ~14% of the company's fund capital. This development is naturally concerning, even though it is not the company's most important product category. We remind you that eQ's most important product category (PE) is not visible in the fund report, and its sales play a thoroughly decisive role for the group. Both open-ended real estate funds also have significant redemption queues.
Evli's net subscriptions were up by 11 MEUR in October, which is a very weak level for Evli. Evli's 12-month net inflows dropped from ~0.9 billion to 0.65 billion as the strong month of October last year rolled out of the review period. Net subscriptions for the current year remain at only ~300 MEUR, and new sales also remained very modest in the Q3 report. In our view, the issue is not so much with new sales as it is with the high volume of redemptions caused by the uncertain market environment among institutional investors. Overall, however, Evli should be capable of a clearly better sales performance.
In October, United Bankers' own net subscriptions were ~22 MEUR in the red, as redemptions were made particularly from equity funds. For the past 12 months, UB's own net subscriptions are down to just under 10 MEUR, which is a very weak level for the company. Fondita's net subscriptions were negative again (-11 MEUR), and its net subscriptions for the current year now stand at around -117 MEUR, which corresponds to ~40% of its current fund assets. Fourton's cash flows were close to zero, meaning that at the group level, UB's net subscriptions were more than 30 MEUR in the red. We also remind investors that at the beginning of October, UB was forced to postpone redemptions in two of its real estate funds, so taking those into account, the October figures would be even weaker than they are now. Although UB's sales of discretionary wealth management are performing well, they cannot compensate for the weakness in fund sales. Sales of the company's spearhead funds in particular are currently difficult across the board.
We remind investors that the development of fund capital should be monitored over a longer period, in addition to individual months. The significance of mutual fund capital also varies significantly between companies.