Privacy preferences
Inderes uses cookies to provide a better user experience and a personalised service. By consenting to the use of cookies, we can develop an even better service and will be able to provide content that is interesting to you.
  • Forum
  • Premium
  • Stock Markets
    • MarketsLive prices, indices, and market performance
    • Stock CalendarUpcoming earnings, listings, and corporate events
    • Dividends CalendarFuture and past dividends
  • Companies
    • CompaniesBrowse and filter the full list of listed companies
    • DiscoveryInspiration for your next investment
    • IPOsNew listings and upcoming public offerings
    • AGM InvitationsAnnual general meeting dates and shareholder info
  • Stock Research
    • ResearchExpert stock analysis and recommendations
    • ArticlesNews, insights, and market commentary
    • PortfolioInderes model portfolio
  • Learn about investing
    • Analysis SchoolLearn how to read and understand stock analysis
    • inderesTVVideo hub for stock research, analysis, and expert commentary
    • TranscriptsFull text records of earnings calls and investor meetings
    • Stock ComparisonCompare financials and performance across multiple stocks
    • Earnings SeasonCompare EPS estimates to reported results
    • Insider TransactionsTrack buying and selling activity by company insiders
    • Short SellingSee which listed companies have disclosed short interest
    • Virtual Analyst ChatAsk questions and get instant AI-powered investment insights
    • Compound Interest CalculatorSee how your savings grow with the power of compound interest.
Find us on social media
  • Inderes Forum
  • Youtube
  • Facebook
  • X (Twitter)
Get in touch
  • info@hcandersencapital.dk
  • Bredgade 23B, 2. sal
    1260 København K
Inderes
  • About us
  • Our team
  • Careers
  • Inderes as an investment
  • Services for listed companies
Our platform
  • FAQ
  • Terms of service
  • Privacy policy
  • Disclaimer

Inderes’ Disclaimer can be found here. Detailed information about each share actively monitored by Inderes is available on the company-specific pages on Inderes’ website. © Inderes Oyj. All rights reserved.

Scanfil Q4'24 preview: Forecasts show a moderate turnaround for Q4 and this year

SCANFLAnalyst Comment19.02.2025, 12.04
Antti ViljakainenHead of Research
Discuss

Scanfil

Translation: Original published in Finnish on 2/19/2025 at 7:20 am EET.

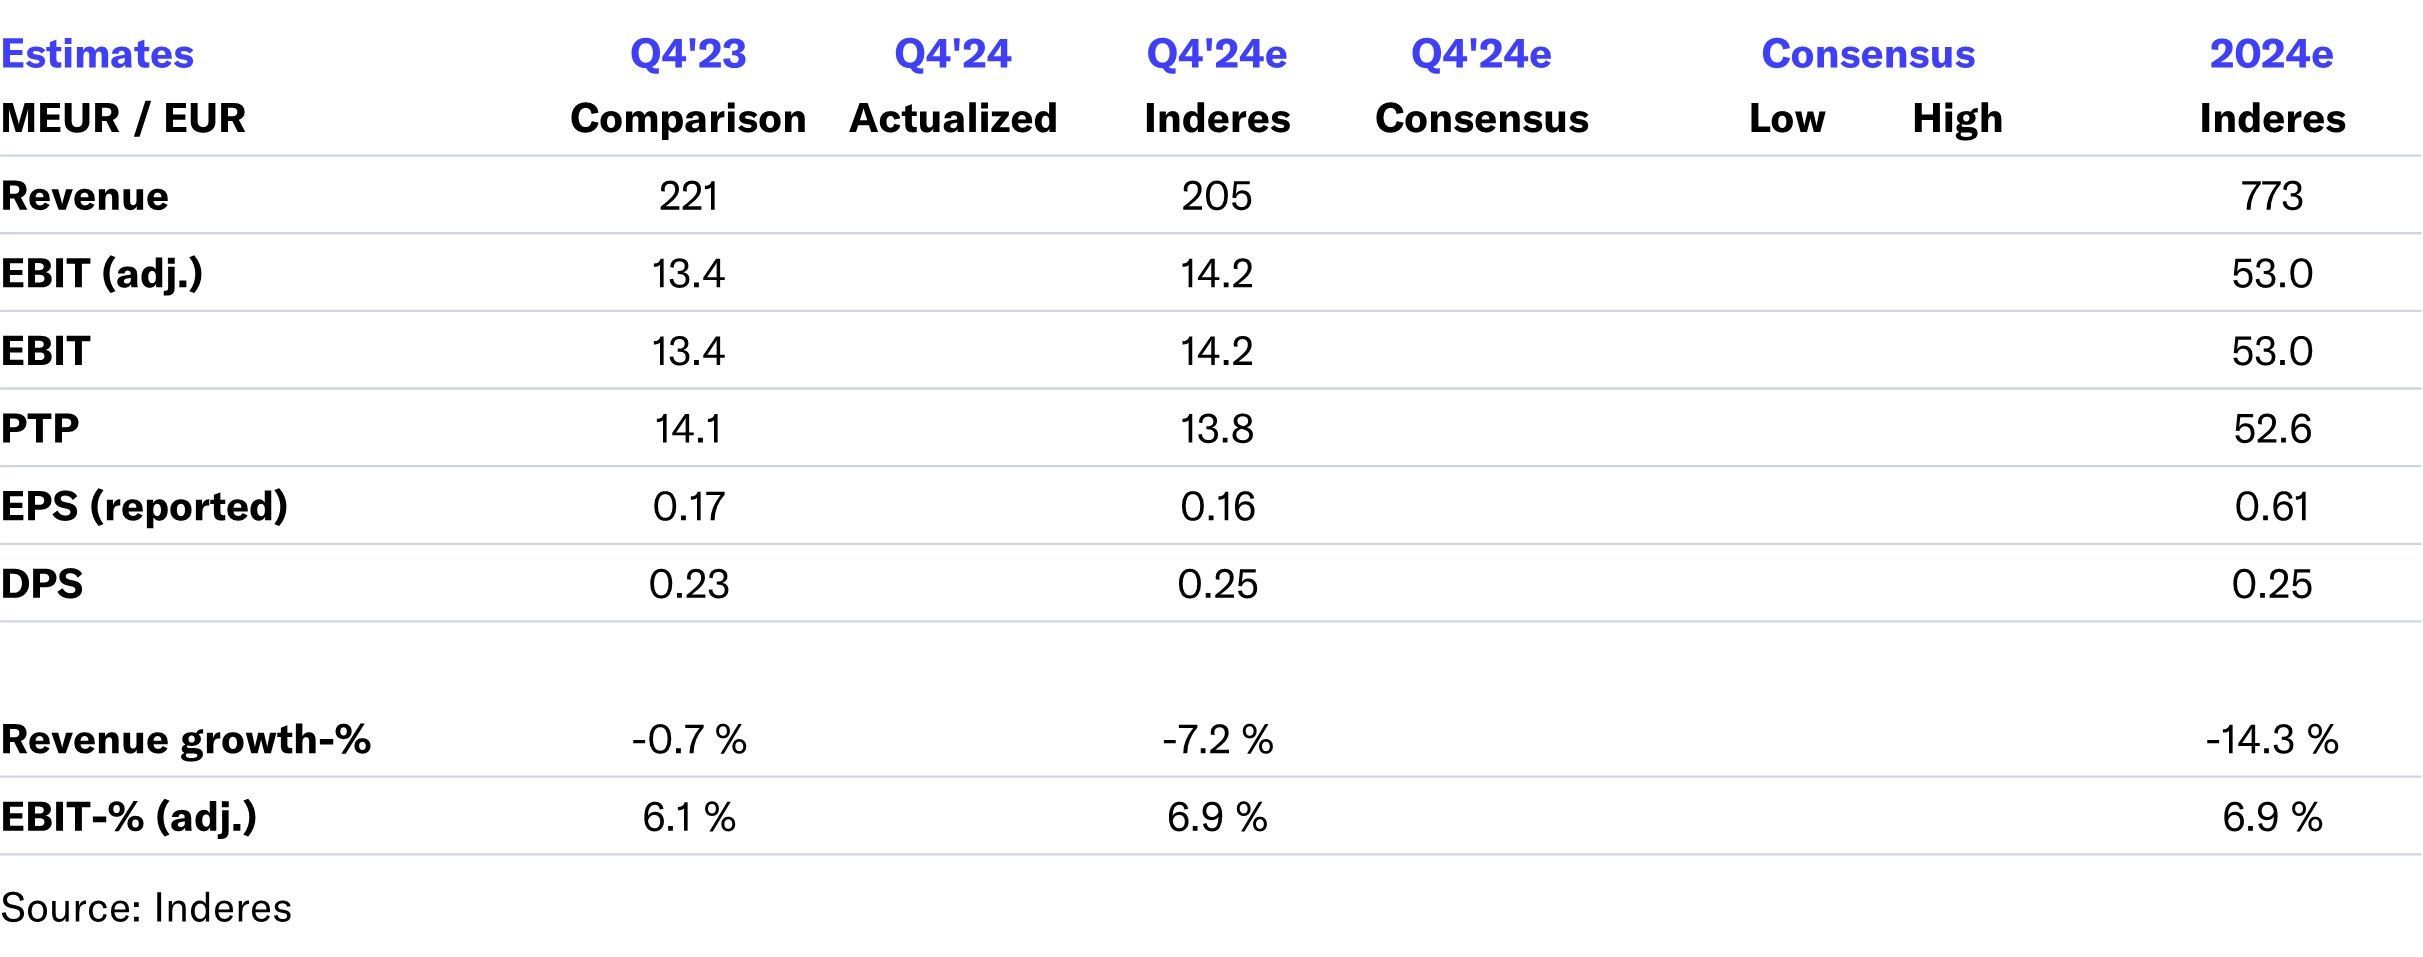
Scanfil will publish its Q4 report on Friday at around 8:00 am EET. Q4 has been the strongest quarter of last year for the company. We expect Scanfil's Q4 earnings to have turned slightly positive, driven by the SRX acquisition and improved profitability, although revenue continued to decline despite inorganic growth due to a weaker market environment compared to the same period last year. Given the very narrow guidance refined in December, the surprise momentum in Q4 operating numbers is very low (and positive for earnings relative to our forecasts). We expect Scanfil to increase the dividend slightly to EUR 0.25 per share. Also in Scanfil's case, the main role is played by the guidance, which, in order to meet our and market expectations, should promise growth and earnings growth for this year.

Revenue has continued to fall despite inorganic growth

Scanfil's demand situation has remained relatively weaker than in a good comparison period, as the company's customer base in the technology industry is largely flat in 2024. In addition, some value chains may still have needed to reduce inventories. Similarly, the SRX acquisition added approximately 4 to 5 percentage points of inorganic growth. Reflecting this overall picture, we expect Scanfil's Q4 revenue to decline by 7% to 205 MEUR, which would put the company at the upper end of its implied guidance range. Revenues in Energy&Cleatech and Industrial are estimated to have continued to decline, while we expect MedTech&Life Science to achieve slight growth towards the end of the year. 

Favorable profitability trend continued in Q4

We estimate Scanfil's adjusted EBIT for Q4 at EUR 14.2 MEUR, which represents a profit growth of around 6% from a satisfactory comparison level. We expect earnings growth to be driven primarily by the inorganic contribution from SRX. Our forecast is right at the lower end of the company's implied guidance range, so there are only positive risks to the Q4 EBIT forecast. In the comparison period, Scanfil's Q4 profitability was impacted by one-time restructuring charges of around 1.5 MEUR, but we estimate that the benefits of the absence of these charges were roughly offset by the decline in revenue in absolute terms. However, we expect the company's profitability to have increased in Q4, as in other quarters last year, driven by productivity improvements, and to be at a fairly good level with an EBIT margin of around 6.9% (versus the company's target of 7-8% EBIT%).  

On the lower lines, our financial expense and tax forecasts are in line with Scanfil's normalized levels, although non-cash FX differences that are not material to the company as a whole could impact financial expense and EPS. We expect Scanfil's EPS to have declined from the comparison period, which was supported by positive financial items, and to have been EUR 0.16 per share. In terms of cash flow, the report should be good as the decline in revenue has probably freed up working capital and, even on a seasonal basis, Scanfil's cash flow usually strengthens towards the end of the year.

The midpoints of the guidance should indicate revenue and profit growth

Scanfil has traditionally guided its revenue and adjusted EBIT with numerical ranges. This year, we expect Scanfil's revenue to grow by 9% to 844 MEUR and adjusted EBIT to grow by 11% to 59 MEUR. Just under half of the revenue and profit growth in our forecast comes from the SRX acquisition. We estimate that consensus expectations are broadly in line with our forecasts. Thus, to meet expectations, Scanfil should guide for roughly 780-880 MEUR in revenue and 55-65 MEUR in adjusted EBIT. In our view, a moderate turnaround in organic and earnings growth is a realistic assumption given the fundamental improvement in European economic growth in the second half of the year at the latest, the company's promising sales performance in the past year, and the Q4 reports reflecting the largely cautious demand optimism of the company's customers.

Scanfil is an international electronics contract manufacturer, specializing in industrial and B2B customers. Services include manufacturing of end products and components such as PCBs. Manufacturing services are the core of the company, supported by design, supply chain and modernization services. The company operates globally in Europe, America and Asia. Customers are primarily found in the process automation, energy efficiency, green efficiency and medical segments.

Read more on company page

Key Estimate Figures27.10.2024

202324e25e
Revenue901.5772.7844.0
growth-%6.8 %-14.3 %9.2 %
EBIT (adj.)61.353.058.7
EBIT-% (adj.)6.8 %6.9 %7.0 %
EPS (adj.)0.740.610.68
Dividend0.230.250.27
Dividend %2.9 %2.1 %2.3 %
P/E (adj.)10.619.117.1
EV/EBITDA7.010.69.4

Forum discussions

For Western companies selling to the Chinese market, local production is a competitive advantage that has become increasingly prominent in recent...
yesterday
by Pasi Hiedanpää
8
sttinfo.fi Scanfil laajentaa yhteistyötään Brukerin kanssa APAC-alueelle vastatakseen... Scanfil laajentaa yhteistyötään Brukerin Advanced X...
yesterday
by Cadel
12
Hanza, a peer company to Scanfil and Incap, published its Q3 results today, where revenue grew by 77% driven by acquisitions to SEK 2,487 million...
10/27/2026, 8:58 AM
by Tuukka Lundell
10
Antti and Tuukka have published a new company report on Scanfil following Q3 Scanfil’s Q3 figures published on Friday were operationally in ...
10/26/2026, 5:57 AM
by Sijoittaja-alokas
5
Here is Carnegie’s analysis on Scanfil following Q3 Scanfil’s Q3 report showed several encouraging signs for growth ahead, including: 1) organic...
10/24/2026, 1:15 PM
by Sijoittaja-alokas
5
Here are Antti’s and Tuukka’s quick comments on Scanfil’s Q3 results Scanfil released its Q3 report this morning. Driven by acquisitions, the...
10/23/2026, 6:26 AM
by Sijoittaja-alokas
8
And here are Scanfil’s Q3 key figures: July–September Revenue was EUR 252.2 million (191.3), an increase of 31.8% Revenue grew organically by...
10/23/2026, 5:03 AM
by Jukka
13