Gabriel Q4'25/26 preview: Focus shifts to 2026/27 guidance after a strong close to the year


Summary
- The analyst expects Q4 continuing revenue of MDKK 142, up 12.7% year on year, and full-year continuing EBIT at the midpoint of raised guidance of MDKK 50–52.
- For 2026/27, the analyst forecasts revenue of MDKK 575 and EBIT of MDKK 58.6. The company’s guidance and any financial targets for the continuing business are key points to watch.
- The analyst reiterates an Accumulate recommendation and DKK 270 target price, versus a share price of DKK 230. The final accounting for the Leggett & Platt transaction and its balance-sheet impact are also in focus.
This content is generated by AI. You can give feedback on it in the Inderes forum.
Gabriel Holding will publish its annual report for 2025/26 on Wednesday 25 November. Following the upgrade on 6 October, we expect the report to confirm Q4 revenue growth of around 13% and full-year continuing EBIT at the midpoint of the raised MDKK 50-52 range. With the headline figures largely known, our attention turns to the guidance for 2026/27, the potential financial targets for the continuing business and the final accounting for the Leggett & Platt transaction. We reiterate our Accumulate recommendation and target price of DKK 270 ahead of the report.
A genuine step up in growth rather than a soft comparison
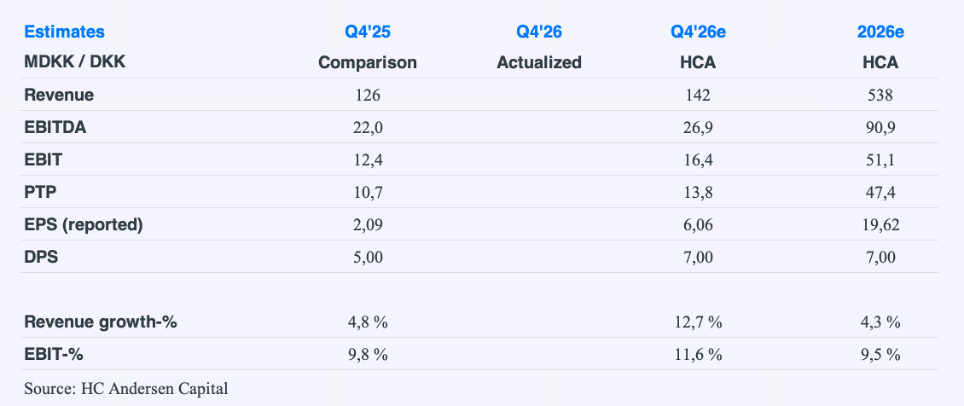
We expect Q4 revenue from continuing operations of MDKK 142, corresponding to growth of 12.7% y/y (Q4'24/25: MDKK 126) and in the middle of the MDKK 141-143 implied by the upgraded guidance. This takes full-year revenue to MDKK 538, up 4.3% (2024/25: MDKK 516). Unlike Q3, where growth largely reflected a soft comparison base, the Q4 growth comes on top of 4.8% growth in the same quarter last year, which in our view makes the acceleration more meaningful. Management attributes the growth to progress across all parts of the continuing business. The company has not yet broken it down by region or driver, which we will look for in the report. At Q3, Europe and North America grew while Asia was flat. We are particularly interested in whether Q4 marks the point at which the key account managers hired over the past year begin converting the pipeline, as their revenue contribution typically lags by two to three quarters.
Operating leverage lifts Q4 to the strongest margin of the year
We estimate Q4 EBITDA of MDKK 26.9 (Q4'24/25: MDKK 22.0) and EBIT of MDKK 16.4 (Q4'24/25: MDKK 12.4), implying an EBIT margin of 11.6% (Q4'24/25: 9.8%) and in line with the MDKK 15.4-17.4 implied by guidance. Higher volumes on a largely fixed cost base explain most of the improvement. The gross margin should remain supported by the favorable customer and product mix that lifted it to 55.2% after nine months (9M’24/25: 54.7%). We forecast pre-tax profit of MDKK 13.8 (Q4'24/25: MDKK 10.7) and EPS of DKK 6.06 (Q4'24/25: DKK 2.09), taking full-year continuing EPS to DKK 19.62 (2024/25: DKK 13.13). We expect a proposed dividend of DKK 7.00 per share, corresponding to a payout ratio of around 36% (2024/25: DKK 5.00, around 38%). The Q4 result from discontinued operations will include an estimated gain of around MDKK 5 on the sale of the European FurnMaster activities, before advisory costs, as the goodwill write-down tied to these activities was already taken at Q3.
2026/27 guidance and the balance sheet effect of the sale in focus
With the 2025/26 figures largely known after the upgrade, what matters most to us is the guidance for 2026/27 and whether the Q4 momentum carries into the new year. We estimate revenue of MDKK 575 (+6.8%) and EBIT of MDKK 58.6, a 10.2% margin. Given the wide ranges the company issued a year ago (revenue MDKK 510-550, EBIT MDKK 40-55), we expect the initial guidance to bracket our estimates rather than pin them down, and we see the midpoints as the more telling signal. The possible introduction of financial targets for the continuing business would, in our view, be the most important new information, as it would anchor the margin trajectory we forecast towards a peak of 11.5%. We also look for the final transaction accounting and confirmation of the reduction in net debt following the sale, as well as an update on the sales process for the Mexican subsidiary. While buyback programmed are often renewed alongside annual results, the current programmed runs until March 2027, and with only around 11,000 shares repurchased against a mandate of up to 94,500, we see little to suggest a new programmed will be announced. With gearing substantially reduced, capital allocation between dividends, buybacks and growth investments is a further watchpoint. With the share trading at DKK 230 against our target price of DKK 270, we see the 2026/27 guidance as the main factor that could change our view.
Disclaimer: HC Andersen Capital receives payment from Gabriel for a DigitalIR and research agreement. /Rasmus Køjborg and Victor Skriver, 08:00 17/11/2026.